Individual and family plans
Private PPO and Marketplace options matched to your household's health needs, preferred doctors and budget.
Get a family quoteLicensed in Florida and 32+ states
I'm David Skoczylas. I compare plans across multiple carriers, explain every option in plain language, and stay with you long after you enroll. My help costs you nothing.
Question 1 of 4
Question 2 of 4
Question 3 of 4
Question 4 of 4
I'll compare options that match what you told me and walk you through them.
Send my answers to David Call insteadSound familiar?
If any of these sound familiar, you didn't do anything wrong. The process is confusing by design.
You fill out a quote form online
Your number gets passed to a dozen call centers. When you contact me, you talk to me, and your information goes nowhere else.
You check the Marketplace
Without a subsidy, ACA pricing can be steep. There may be options, or savings, that nobody has shown you yet.
You pick something anyway
A low premium can hide a deductible so high you pay twice: once every month, and again the day you need care.
If you're generally healthy, a private, medically underwritten PPO can offer nationwide provider access at a lower monthly cost than an unsubsidized Marketplace plan.
Most people outside the industry never hear about this option. I put it side by side with Marketplace plans so you see real numbers before you decide, including the trade-offs.
See if you qualify| Private PPO | ACA Marketplace | |
|---|---|---|
| Who can enroll | Based on health history | Anyone, guaranteed |
| Pre-existing conditions | Can be covered, depending on the condition. We review it together by phone. | Always covered |
| Subsidies | Not available | Available by income |
| When you can enroll | Year-round | Open or special enrollment |
| Best fit for | Healthy people without subsidies | Subsidy-eligible or ongoing health needs |
Private plans are non-ACA products and don't include all Essential Health Benefits. I'll always tell you which one fits your situation.
Coverage options
Whether you're protecting a family, working for yourself, or running a team, I match you with a strategy, not just a policy.
Private PPO and Marketplace options matched to your household's health needs, preferred doctors and budget.
Get a family quoteSide-by-side Marketplace comparisons with premium tax credit and cost-sharing reduction guidance built in.
Check my subsidyPortable coverage for freelancers, contractors and owners who don't have an HR department.
Get a 1099 quoteGroup and individual structures compared so you choose what fits your team and budget.
See business optionsLost a job or leaving one? Compare options that can cost far less than COBRA, with no gap in coverage.
Compare to COBRAWho I work with
Every household and business is different. Here are the folks I help most, and what usually fits them best.
Straightforward plans for everyday households, couples and kids.
Portable coverage built for freelancers and independent pros.
Group and individual options that grow with your team.
Flexible, year-round enrollment for variable-income work.
Nationwide networks that travel with your schedule.
Bridge coverage for the years before Medicare starts.
Wherever life has you right now
A minute with me
No jargon, no sales pitch. Just the questions I get asked most.
A well-built benefits package is one of the best investments a business can make, in its people and its bottom line.
Benefits are often what decides between two job offers. A thoughtful plan shows your team you're invested in them.
Group plans, HSAs and Section 125 structures can lower the tax burden for you and your employees.
No two businesses share the same headcount, budget or culture, so no two plans should look alike.
Most people have only experienced one kind of insurance shopping. Here's how a guided relationship compares.
Simple process
Five clear steps, from first call to ongoing support.
Call, text or send the form. It's a friendly, no-pressure conversation.
I learn your health needs, doctors, budget and comfort with risk.
You get a short list of plans, explained side by side in plain language.
I handle the paperwork and walk you through every step.
I'm here for claims questions, changes and your annual review.
Learning center
Straight answers to the questions I hear most.
Once you understand five terms, most plan documents start to make sense.
Start with how your family really uses care: pediatric visits, sports injuries, prescriptions or specialist appointments all change which plan makes sense.
Most ACA-compliant plans cover wellness visits, many vaccines and standard screenings at no cost, even before the deductible.
Confirm your pediatrician is in-network, well-child visits are covered, and whether pediatric dental and vision are included.
Open Enrollment is the yearly window, usually in the fall, when anyone can sign up for or switch Marketplace plans. Employer plans run on their own schedule.
A qualifying life event typically opens a 30 to 60 day window. Common events include marriage or divorce, having or adopting a child, losing other coverage, moving, or an income change that affects subsidies.
Premium tax credits lower your monthly premium based on household income. Many middle-income households qualify without realizing it.
Cost-sharing reductions are a separate discount on Silver plans that lower your deductible, copays and out-of-pocket maximum.
Bronze has the lowest premium and highest costs when you use care. Silver sits in the middle and is the only tier with cost-sharing reductions. Gold and Platinum cost more monthly and less when you see a doctor.
Having a baby opens a Special Enrollment Period. Most plans give you 30 to 60 days from the birth to add your child. Miss it and you may wait until the next open enrollment.
Well-child visits usually happen at 1 week and at 1, 2, 4, 6, 9 and 12 months. Most ACA-compliant plans cover them as preventive care.
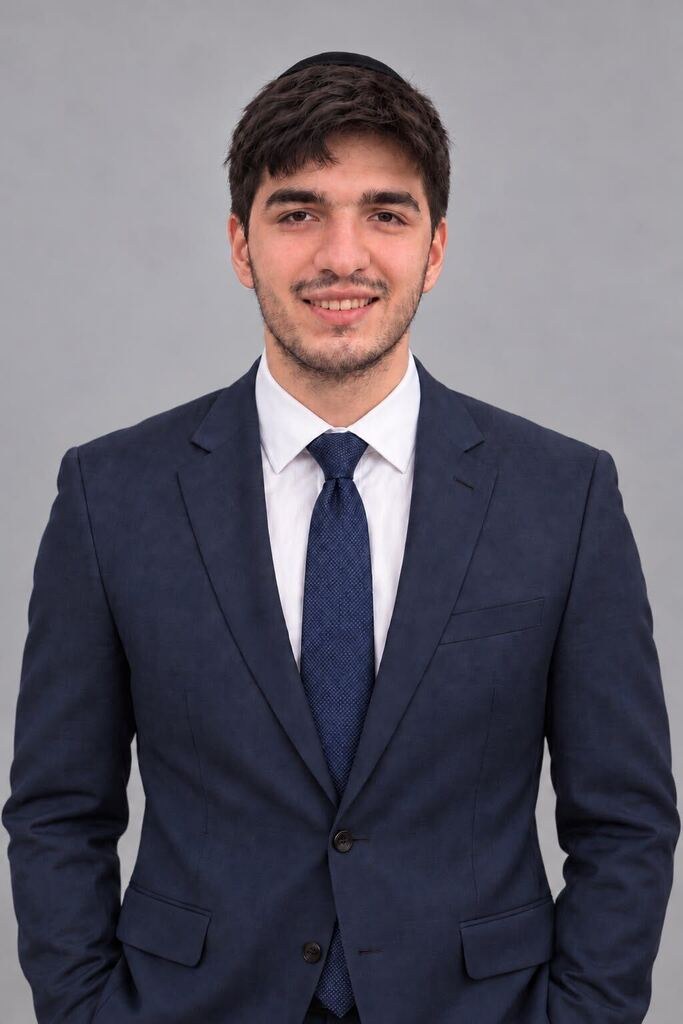
I'm David Skoczylas, a Florida-licensed health insurance agent (NPN 22218464), not a doctor. I started Skoczylas Health because people deserve clear answers about their coverage, without sales pressure.
As an independent advisor, I'm not tied to a single carrier. I compare private and Marketplace plans, explain the trade-offs in plain language, and help you choose with confidence. When you call, you reach me, and I'm still here after you enroll for billing questions, plan changes and renewals.
View my credentials and how to verify them
To be clear about a common mix-up: I'm an insurance agent, not a physician. Skoczylas Health is an independent insurance agency and is not a medical practice or doctor's office.
Health and contact details are sensitive. Here's exactly how I handle them.
What you tell me is used only to find your coverage. It's never passed to marketers or lead sellers.
Form submissions travel over an encrypted connection and are read by me, not a shared call center.
Want your information corrected or deleted? Call, text or email and I'll take care of it.
Client reviews
Quick answers
No. I'm paid by the insurance carriers, so my guidance is free to you and your premium is the same as if you enrolled on your own.
We start with a conversation about your health needs, budget and preferred doctors. Then I narrow the options and explain the trade-offs so the decision feels clear.
Marketplace plans are guaranteed issue, cover pre-existing conditions and can come with income-based subsidies. Private PPOs are medically underwritten, which means your good health can earn you better rates, often with nationwide PPO access. I'll compare both for you.
Yes. I build group benefits strategies for businesses of all sizes, compare carriers, structure plans for tax efficiency and manage the account year-round.
Not necessarily. Losing coverage opens a Special Enrollment Period, and private plans may also be available. We can compare them to COBRA's cost before your election window closes.
Yes. I'm available all year for claims questions, billing issues, plan changes and an annual review to make sure your plan still fits.
Absolutely. Because I'm independent, I show you several options side by side so you can compare costs, coverage and networks.
Free & no obligation
Tell me what you're looking for, then pick a time on my calendar on the next screen. I'll call you at your appointment time.
Step 2 of 2
Your answers are already attached to the booking, so you can go straight to choosing a time.
You're booked. A confirmation email is on its way.
Want a faster response?
Text HEALTH INSURANCE to (561) 430-9811 for a free quote.